Economy
UK Investment in Africa Surges as Nigeria Attracts New Business Amid US Trade Decline


UK investment in Africa surges as firms target Nigeria and other nations for growth, driven by reforms, resources, and AfCFTA opportunities amid US pullback

A new wave of UK investment in Africa is unfolding, with Nigeria and other mineral-rich countries fast becoming prime destinations for British businesses seeking growth and diversification beyond traditional markets.
Also read: Africa-Canadian Investment Summit: Peju Oke Visit King Tackie Teiko of Ga Mantse
According to new research by UK-based Strategy Management Partners, over 50% of large British companies are already operating across African markets, with many planning to scale further.
An additional 28% are actively exploring opportunities on the continent but remain cautious due to regulatory complexity and political risk.
Africa’s growing allure stems from three key factors: vast mineral wealth, a youthful population, and bold structural reforms.
The continent holds:
- 30% of global mineral reserves
- 12% of the world’s oil supply
- 65% of arable land, and
- Alabour force projected to account for 25% of the global total by 2035
Seven sectors are emerging as investment hotspots:
Technology, Oil & Gas, Renewable Energy, Agriculture, Manufacturing, Infrastructure, and Strategic Minerals like lithium and cobalt—vital for the global energy transition.
“Africa is no longer just a resource hub,” the report states. “It is becoming a centre of innovation, consumption, and labour.”
Strategy Management Partners surveyed 250 senior UK executives, including CEOs and Heads of Strategy, from firms with annual revenues exceeding £20m.
The findings reveal a major shift in perception: Africa is being redefined from a frontier market into a core strategic region.
“UK businesses are paying attention,” said Muibat Ijaiya, a Partner at the firm. “They see the demographic dividend, infrastructure reforms, and digital revolution as key enablers of long-term return.”
But she stressed that public-private alignment is essential. “Real progress depends on strong cooperation between governments and investors, especially around the African Continental Free Trade Area (AfCFTA).”
This growing UK focus comes amid a sharp downturn in US-Nigeria trade relations. Between January and May 2025, US imports from Nigeria fell by $527 million, a 20% year-on-year drop.
The decline followed US President Donald Trump’s April 2025 executive order imposing a 10% blanket tariff, and a 14% tariff specifically targeting Nigeria due to its trade surplus with the US.
Additional levies may apply to countries aligning with BRICS, where Nigeria is a potential member.
While the US scales back, UK trade missions are filling the gap.
During a recent visit to Nigeria, Mayor of London Sadiq Khan led a delegation of 27 British companies focused on fintech, tech, sustainability, and education.
“Africa has the world’s fastest-growing population and major economic potential,” Khan said. “I’m here to champion deeper UK-Africa ties.”
To accelerate UK investment in Africa, Public-Private Partnerships (PPPs) are being championed as a strategic solution.
Speaking to our correspondent, Babatunji Adegoke, Treasurer of the Nigerian Society of Engineers (Victoria Island), emphasised that PPPs offer a flexible, structured model that can attract Foreign Direct Investment (FDI), particularly in high-potential areas like lithium.
“PPP is no longer optional—it’s a strategic necessity,” he said. “It provides clarity, reduces risk, and channels private capital toward public goals.”
Adegoke highlighted the importance of developing infrastructure—not just for mining, but also for processing, transport, and logistics—making structured PPPs the best route for financing these complex ventures.
He also noted that local professionals must play a bigger role in structuring and managing transactions. “Local insight improves sustainability and ensures that deals serve national interests.”
Despite growing optimism, investors continue to cite several key concerns:
- Regulatory complexity
- Political instability
- Currency volatility
- Cross-border transaction barriers
Yet, the report downplayed some commonly assumed obstacles, like challenges in opening local bank accounts or accessing working capital, suggesting that perceived risks may be higher than real ones in some areas.
Still, the continent’s economic future is not without hurdles. Trade reform, governance, and legal certainty remain crucial to unlocking Africa’s full investment potential.
Governments across Africa are shifting from resource extraction to value-added development. Local beneficiation, processing plants, and regional manufacturing hubs are beginning to take root.
This trend is bolstered by:
- AfCFTA, which now has 23 countries implementing preferential tariffs
- China’s tariff eliminations on imports from 53 African nations
- Renewed industrial policies from South Africa to Nigeria
Strategic minerals like cobalt, manganese, and graphite are placing Africa at the heart of the global clean energy supply chain.
With 70% of Africans under 30, a massive consumer class is emerging, fuelling demand for housing, digital services, transport, and healthcare.
For British businesses with vision and long-term commitment, the opportunities are immense.
As the Strategy Management Partners report concludes:
Also read: “Lights, Camera, Abuja! AICL GMD Attends SIN Premiere, Reinforces Support for Creative Economy”
“Africa’s moment is now. The businesses that move with purpose, partner locally, and stay for the long haul will not just invest—they will become part of Africa’s transformation story.”


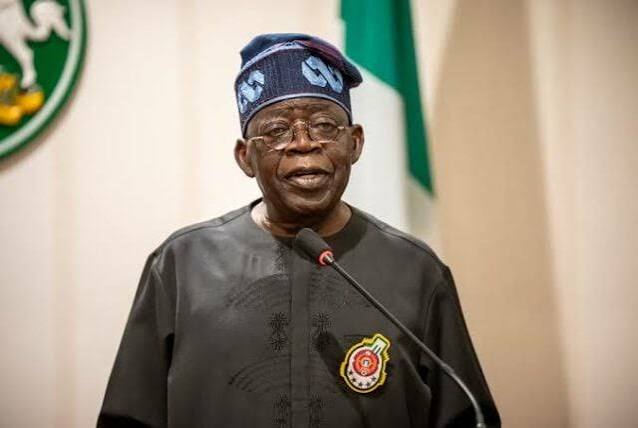
Nigeria investment in youth and local industries is vital to job creation, says FG, urging public-private partnerships and regional industrialisation
The Federal Government has called for increased investment in youth development, small and medium-sized enterprises, technology and local industries to create jobs and strengthen Nigeria’s economic competitiveness.
Also read: Osun amotekun dismisses officer over gross misconduct
The Minister of State for Foreign Affairs, Ambassador Sola Enikanolaiye, made the call during a panel discussion titled “From Trade to Value Chains: Building Regional Industries to Compete Globally” at the 32nd Nigerian Economic Summit, held under the sub-theme, “Invest Nigeria”.
In a statement issued on Tuesday and signed by his Special Assistant on Digital Media and Public Diplomacy, Raphael Oni, Enikanolaiye said Nigeria needed stronger partnerships between the public and private sectors to mobilise the capital required for sustainable economic growth.
He argued that the country must move beyond trading raw materials towards building industries that process local resources into finished products for domestic consumption and export.
According to the minister, investment from both domestic businesses and foreign sources would be necessary to expand industrial capacity, create employment opportunities and improve living standards.
“In advancing our country, we don’t talk enough to one another in terms of constructive conversation and dialogue. We believe that partnership which allows government to engage deeper and stronger with the private sector is critical. Government alone cannot alone raise the resources needed for shared prosperity,” he said.
Enikanolaiye added that domestic capital mobilisation was as important as attracting foreign investment.
He identified Nigeria’s youthful population as a major asset that could accelerate industrialisation if supported by investments in education, skills development, innovation and entrepreneurship.
“Our youth population is very critical – a vibrant population. We need to invest more in human capital, focusing on Small and Medium Scale Enterprises, technology, innovation and creativity. By so doing, we will be able to generate more employment for the youth and also raise more wealth and income,” he said.
On foreign policy, the minister said the administration had reordered its four-point 4D doctrine to place the welfare and prosperity of Nigerians at the centre of the country’s international engagements.
The framework focuses on Demography, Development, Democracy and Diaspora.
Enikanolaiye said democratic governance should produce tangible economic benefits for citizens rather than remain an end in itself.
“Democracy is good, but it is a means to an end, not an end in itself. Democracy must deliver on core priorities of economic development and economic prosperity to our people,” he said.
The minister also emphasised the importance of macroeconomic stability and reliable economic data in helping businesses assess investment opportunities and make long-term plans.
He said Nigeria had recorded improvements in macroeconomic stability and that inflation was coming down, although he did not provide supporting figures in the statement.
Enikanolaiye further called for reforms to make the Ministry of Foreign Affairs more responsive to Nigerians and strengthen its engagement with businesses.
He said cooperation between the government and private sector, alongside partnerships with neighbouring countries and other international markets, could help Nigeria expand its industrial base and improve its access to regional and global markets.
Also speaking at the summit, the President of the Economic Community of West African States Commission, General Birame Diop, called for greater emphasis on industrialisation to create jobs and strengthen regional trade.
His remarks were delivered by the ECOWAS Commissioner for Economic Affairs and Agriculture, Dehpue Yenpea Zuo.
Diop argued that trade agreements alone could not deliver widespread employment and economic growth without industries capable of processing raw materials and producing goods.
“Trade agreements do not create jobs; industries do,” he said.
He noted that intra-African trade accounted for about 15 per cent of the continent’s total trade, compared with more than 60 per cent in Europe and Asia.
He attributed the gap partly to the limited scale of regional industries.
According to Diop, the regional market, with more than 300 million consumers, provides an opportunity for West African manufacturers to expand production before competing across the continent under the African Continental Free Trade Area.
He outlined four priorities for advancing regional industrialisation: implementing existing trade agreements, including commitments on border management; developing value chains in sectors where West Africa has a competitive advantage; improving access to finance for businesses and producers; and measuring progress through jobs created and goods processed within the region.
Also read: Osun amotekun dismisses officer over gross misconduct
Diop said converting trade commitments into productive industries would be essential to expanding employment, increasing regional economic activity and strengthening West Africa’s competitiveness in global markets.

Cash outside Nigerian banks rose to N4.92tn in September 2026 as Nigeria’s broad money supply increased to N146.6tn, CBN data show
Cash outside Nigerian banks rose to N4.92tn in September 2026, an increase of N48.73bn from the N4.87tn recorded in August, according to monetary data published by the Central Bank of Nigeria.
Also read: UCL: Nico Paz Scores Twice as Como Crush Man United
The latest figures also showed an expansion in Nigeria’s broad money supply, which increased to N146.6tn in September from N139.09tn in the previous month.
The growth represents an increase of N7.51tn within one month, reflecting a broader expansion in the amount of money circulating across the economy.
The CBN data further showed that narrow money, which consists of currency in circulation and highly liquid deposits, rose to N44.05tn in September from N43.11tn in August.
Cash held outside banks refers to physical currency kept by individuals and businesses rather than within the banking system.
Broad money, by contrast, covers a wider range of monetary assets, including cash, demand deposits, savings and time deposits, as well as foreign currency deposits.
Nigeria’s broad money supply increased by 18.3 per cent between January and September, rising from N123.95tn to N146.6tn, the data indicated.
The latest increase followed the CBN’s decision in September to reduce its benchmark interest rate by 350 basis points, bringing it down from 26.5 per cent to 23 per cent.
The reduction was reported as the largest cut in the benchmark rate since December 2006.
Despite the rate cut, the Monetary Policy Committee retained the Cash Reserve Requirement for commercial banks at 45 per cent and merchant banks at 16 per cent.
The committee also maintained the 75 per cent reserve requirement on non-Treasury Single Account public-sector deposits.
The Cash Reserve Requirement determines the proportion of eligible deposits that banks must hold as reserves with the central bank.
It is one of the monetary policy tools used to influence banking-sector liquidity and credit conditions.
The rise in cash outside Nigerian banks formed part of the broader increase in money supply.
Also read: UCL: Nico Paz Scores Twice as Como Crush Man United
However, the figures alone do not establish why households and businesses held more physical cash or how much of the increase was driven by spending, savings behaviour or other economic factors.
-
Politics3 years ago
13 Ondo Assembly Members Disown Endorsement of Aiyedatiwa
-
Politics3 years ago
APC Group, Ondo Govt, Quarrel Over Money for Endorsement
-

 Trending News5 years ago
Stop unsavoury, inciting statements – DSS warns
-

 Others5 years ago
Adron Homes Celebrates 10 Years Of Housing Excellence
-

 Humanity5 years ago
President Buhari Commiserates With Ambassador Maureen Tamuno Over The Loss Of Her Father
-

 Others7 years ago
EX- CUSTOMS BOSS, IBRAHIM MERA’S DWINDLING FAME
-

 Business3 years ago
Bigi Carbonated Soft Drinks Treats 40 Consumers to an Epic Easter Movie Hangout
-

 Business2 years ago
Wema Bank Shines at Global SME Finance Forum Conference Awards 2024 …Awarded: • SME Financier of the Year (Africa) • Platinum Award for Best Financier for Women Entrepreneurs (Africa)