Economy
Rivers Strengthens Drive for Investor-Friendly Business Environment

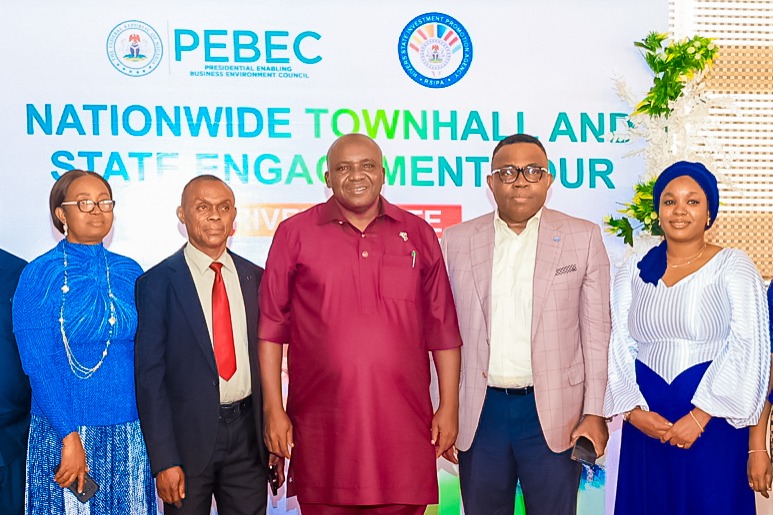
Fubara reaffirms commitment to business-friendly reforms as Rivers State seeks to attract investment, create jobs and boost economic growth

Rivers State Governor Siminalayi Fubara on Friday reaffirmed his administration’s commitment to business-friendly reforms, declaring that the state is focused on building a transparent, predictable and investment-friendly environment capable of driving sustainable economic growth.
Also read: Nigerian Navy Discovers Negative Explosives Camp in Rivers
Fubara made the pledge in Port Harcourt during a Technical Workshop on Business-Enabling Reforms and Investment Competitiveness organised by the Presidential Enabling Business Environment Council (PEBEC) in partnership with the Rivers State Investment Promotion Agency (RSIPA).
Represented by the Secretary to the State Government, Dr Dagogo Wokoma, the governor said Rivers State remains committed to strengthening policies and institutions that will encourage enterprise growth, attract investors and create long-term economic opportunities.
According to Fubara, the state possesses significant economic advantages, including a vibrant population, abundant natural resources, strategic maritime infrastructure and a strong entrepreneurial culture.
“As one of Nigeria’s leading commercial and industrial hubs, Rivers State possesses enormous potential. Our responsibility is to transform these advantages into sustainable economic opportunities through deliberate reforms, strong institutions and effective governance,” he said.
The governor noted that attracting both local and foreign investment remains central to his administration’s economic agenda, stressing that sustainable development depends on creating an environment where businesses can flourish.
He added that successful economies across the world have demonstrated that growth is accelerated when governments establish the right conditions for private sector participation and innovation.
Fubara said the workshop provided an important opportunity for stakeholders to identify obstacles to investment, exchange practical experiences and develop solutions that will strengthen the state’s economic competitiveness.
The governor also emphasised the need to align state policies with global best practices while ensuring that reforms remain responsive to local realities and developmental priorities.
Speaking at the event, the Director-General of the Presidential Enabling Business Environment Council, Princess Zahrah Mustapha Audu, commended the Rivers State Government for creating a platform to engage investors, policymakers and business leaders on strategies for improving the investment climate.
Audu said PEBEC was established to strengthen enterprises and unlock economic opportunities across Nigeria through targeted reforms that reduce bottlenecks and improve the ease of doing business.
She reiterated the Federal Government’s commitment to implementing economic policies designed to enhance investor confidence and support national economic growth.
According to her, meaningful economic transformation can only be achieved through stronger collaboration and alignment between federal, state and local governments.
Also addressing participants, the Director-General of the Rivers State Investment Promotion Agency, Peterside Chamberlain, said the agency remains focused on creating an enabling environment where businesses can thrive and employment opportunities can expand.
“We know that private sector investment is the driver of economic development and progress. We are working to make Rivers State the preferred investment destination,” Chamberlain said.
The workshop forms part of ongoing efforts by both federal and state authorities to improve Nigeria’s business environment amid increasing competition for domestic and foreign capital.
Over the years, PEBEC has championed reforms aimed at simplifying regulatory processes, improving transparency and reducing the cost of doing business across the country.
For Rivers State, one of Nigeria’s most important economic centres due to its oil and gas resources, ports and industrial activities, attracting new investment is viewed as critical to diversifying the economy, creating jobs and increasing internally generated revenue.
Also read: Rivers Police Prohibit Covered Plates, Unregistered Vehicles
Stakeholders at the workshop expressed optimism that stronger institutional coordination and sustained reforms would help unlock the state’s vast economic potential and position it as a leading investment destination in Nigeria and beyond.


FCCPC fuel price monitoring intensifies as Tunji Bello urges Nigerian refiners and marketers to reflect falling crude prices in petrol costs

Nigeria investment in youth and local industries is vital to job creation, says FG, urging public-private partnerships and regional industrialisation
The Federal Government has called for increased investment in youth development, small and medium-sized enterprises, technology and local industries to create jobs and strengthen Nigeria’s economic competitiveness.
Also read: Osun amotekun dismisses officer over gross misconduct
The Minister of State for Foreign Affairs, Ambassador Sola Enikanolaiye, made the call during a panel discussion titled “From Trade to Value Chains: Building Regional Industries to Compete Globally” at the 32nd Nigerian Economic Summit, held under the sub-theme, “Invest Nigeria”.
In a statement issued on Tuesday and signed by his Special Assistant on Digital Media and Public Diplomacy, Raphael Oni, Enikanolaiye said Nigeria needed stronger partnerships between the public and private sectors to mobilise the capital required for sustainable economic growth.
He argued that the country must move beyond trading raw materials towards building industries that process local resources into finished products for domestic consumption and export.
According to the minister, investment from both domestic businesses and foreign sources would be necessary to expand industrial capacity, create employment opportunities and improve living standards.
“In advancing our country, we don’t talk enough to one another in terms of constructive conversation and dialogue. We believe that partnership which allows government to engage deeper and stronger with the private sector is critical. Government alone cannot alone raise the resources needed for shared prosperity,” he said.
Enikanolaiye added that domestic capital mobilisation was as important as attracting foreign investment.
He identified Nigeria’s youthful population as a major asset that could accelerate industrialisation if supported by investments in education, skills development, innovation and entrepreneurship.
“Our youth population is very critical – a vibrant population. We need to invest more in human capital, focusing on Small and Medium Scale Enterprises, technology, innovation and creativity. By so doing, we will be able to generate more employment for the youth and also raise more wealth and income,” he said.
On foreign policy, the minister said the administration had reordered its four-point 4D doctrine to place the welfare and prosperity of Nigerians at the centre of the country’s international engagements.
The framework focuses on Demography, Development, Democracy and Diaspora.
Enikanolaiye said democratic governance should produce tangible economic benefits for citizens rather than remain an end in itself.
“Democracy is good, but it is a means to an end, not an end in itself. Democracy must deliver on core priorities of economic development and economic prosperity to our people,” he said.
The minister also emphasised the importance of macroeconomic stability and reliable economic data in helping businesses assess investment opportunities and make long-term plans.
He said Nigeria had recorded improvements in macroeconomic stability and that inflation was coming down, although he did not provide supporting figures in the statement.
Enikanolaiye further called for reforms to make the Ministry of Foreign Affairs more responsive to Nigerians and strengthen its engagement with businesses.
He said cooperation between the government and private sector, alongside partnerships with neighbouring countries and other international markets, could help Nigeria expand its industrial base and improve its access to regional and global markets.
Also speaking at the summit, the President of the Economic Community of West African States Commission, General Birame Diop, called for greater emphasis on industrialisation to create jobs and strengthen regional trade.
His remarks were delivered by the ECOWAS Commissioner for Economic Affairs and Agriculture, Dehpue Yenpea Zuo.
Diop argued that trade agreements alone could not deliver widespread employment and economic growth without industries capable of processing raw materials and producing goods.
“Trade agreements do not create jobs; industries do,” he said.
He noted that intra-African trade accounted for about 15 per cent of the continent’s total trade, compared with more than 60 per cent in Europe and Asia.
He attributed the gap partly to the limited scale of regional industries.
According to Diop, the regional market, with more than 300 million consumers, provides an opportunity for West African manufacturers to expand production before competing across the continent under the African Continental Free Trade Area.
He outlined four priorities for advancing regional industrialisation: implementing existing trade agreements, including commitments on border management; developing value chains in sectors where West Africa has a competitive advantage; improving access to finance for businesses and producers; and measuring progress through jobs created and goods processed within the region.
Also read: Osun amotekun dismisses officer over gross misconduct
Diop said converting trade commitments into productive industries would be essential to expanding employment, increasing regional economic activity and strengthening West Africa’s competitiveness in global markets.

Cash outside Nigerian banks rose to N4.92tn in September 2026 as Nigeria’s broad money supply increased to N146.6tn, CBN data show
Cash outside Nigerian banks rose to N4.92tn in September 2026, an increase of N48.73bn from the N4.87tn recorded in August, according to monetary data published by the Central Bank of Nigeria.
Also read: UCL: Nico Paz Scores Twice as Como Crush Man United
The latest figures also showed an expansion in Nigeria’s broad money supply, which increased to N146.6tn in September from N139.09tn in the previous month.
The growth represents an increase of N7.51tn within one month, reflecting a broader expansion in the amount of money circulating across the economy.
The CBN data further showed that narrow money, which consists of currency in circulation and highly liquid deposits, rose to N44.05tn in September from N43.11tn in August.
Cash held outside banks refers to physical currency kept by individuals and businesses rather than within the banking system.
Broad money, by contrast, covers a wider range of monetary assets, including cash, demand deposits, savings and time deposits, as well as foreign currency deposits.
Nigeria’s broad money supply increased by 18.3 per cent between January and September, rising from N123.95tn to N146.6tn, the data indicated.
The latest increase followed the CBN’s decision in September to reduce its benchmark interest rate by 350 basis points, bringing it down from 26.5 per cent to 23 per cent.
The reduction was reported as the largest cut in the benchmark rate since December 2006.
Despite the rate cut, the Monetary Policy Committee retained the Cash Reserve Requirement for commercial banks at 45 per cent and merchant banks at 16 per cent.
The committee also maintained the 75 per cent reserve requirement on non-Treasury Single Account public-sector deposits.
The Cash Reserve Requirement determines the proportion of eligible deposits that banks must hold as reserves with the central bank.
It is one of the monetary policy tools used to influence banking-sector liquidity and credit conditions.
The rise in cash outside Nigerian banks formed part of the broader increase in money supply.
Also read: UCL: Nico Paz Scores Twice as Como Crush Man United
However, the figures alone do not establish why households and businesses held more physical cash or how much of the increase was driven by spending, savings behaviour or other economic factors.
-
Politics3 years ago
13 Ondo Assembly Members Disown Endorsement of Aiyedatiwa
-
Politics3 years ago
APC Group, Ondo Govt, Quarrel Over Money for Endorsement
-

 Trending News6 years ago
Stop unsavoury, inciting statements – DSS warns
-

 Others5 years ago
Adron Homes Celebrates 10 Years Of Housing Excellence
-

 Humanity5 years ago
President Buhari Commiserates With Ambassador Maureen Tamuno Over The Loss Of Her Father
-

 Others7 years ago
EX- CUSTOMS BOSS, IBRAHIM MERA’S DWINDLING FAME
-

 Business3 years ago
Bigi Carbonated Soft Drinks Treats 40 Consumers to an Epic Easter Movie Hangout
-

 Business2 years ago
Wema Bank Shines at Global SME Finance Forum Conference Awards 2024 …Awarded: • SME Financier of the Year (Africa) • Platinum Award for Best Financier for Women Entrepreneurs (Africa)